
 CJMY
Insurance helps individuals and families manage financial risks that may arise from illness, injury, or the loss of a loved one. Life insurance and medical insurance serve different purposes, yet both can contribute to a more stable financial future. Understanding how these policies work allows people to choose coverage that suits their income, family responsibilities, and long-term plans. Life insurance focuses on providing financial support to beneficiaries after the insured person passes away, whereas medical insurance helps pay for eligible healthcare expenses during the policyholder’s lifetime. People exploring options from providers such as FWD can benefit from understanding these differences before selecting a policy. A clear understanding of insurance coverage makes it easier to prepare for unexpected expenses and protect the financial well-being of family members.
What Is Life Insurance?
Life insurance is a financial agreement between an individual and an insurance company. The policyholder pays premiums according to the terms of the contract, and the insurer provides a death benefit to the named beneficiaries when the insured person dies, subject to the policy conditions. This payment can help surviving family members manage household expenses, repay outstanding loans, cover funeral costs, and fund children’s education. For households that rely heavily on one person’s income, life insurance can provide valuable financial support during a difficult period. The amount of coverage needed varies according to the policyholder’s earnings, debts, dependents, savings, and existing financial commitments. A suitable policy can help reduce the financial pressure placed on loved ones and give them more time to adjust after a significant loss.
Common Types of Life Insurance
Life insurance comes in several forms, each designed to meet different financial needs. Term life insurance provides protection for a specified period, such as 10, 20, or 30 years. It is often more affordable than permanent coverage and may suit individuals who want protection during their working years or while raising children. Whole life insurance can provide lifelong coverage when the policy remains active and its requirements are met. Some policies accumulate cash value, which grows according to the contract’s terms. Universal life insurance offers greater flexibility in premium payments and death benefits, subject to policy rules, charges, and funding requirements. Certain permanent policies allow access to accumulated cash value, though withdrawals and loans may reduce the benefits available later. Comparing these options helps individuals identify a policy that fits their budget and long-term financial goals.
What Is Medical Insurance?
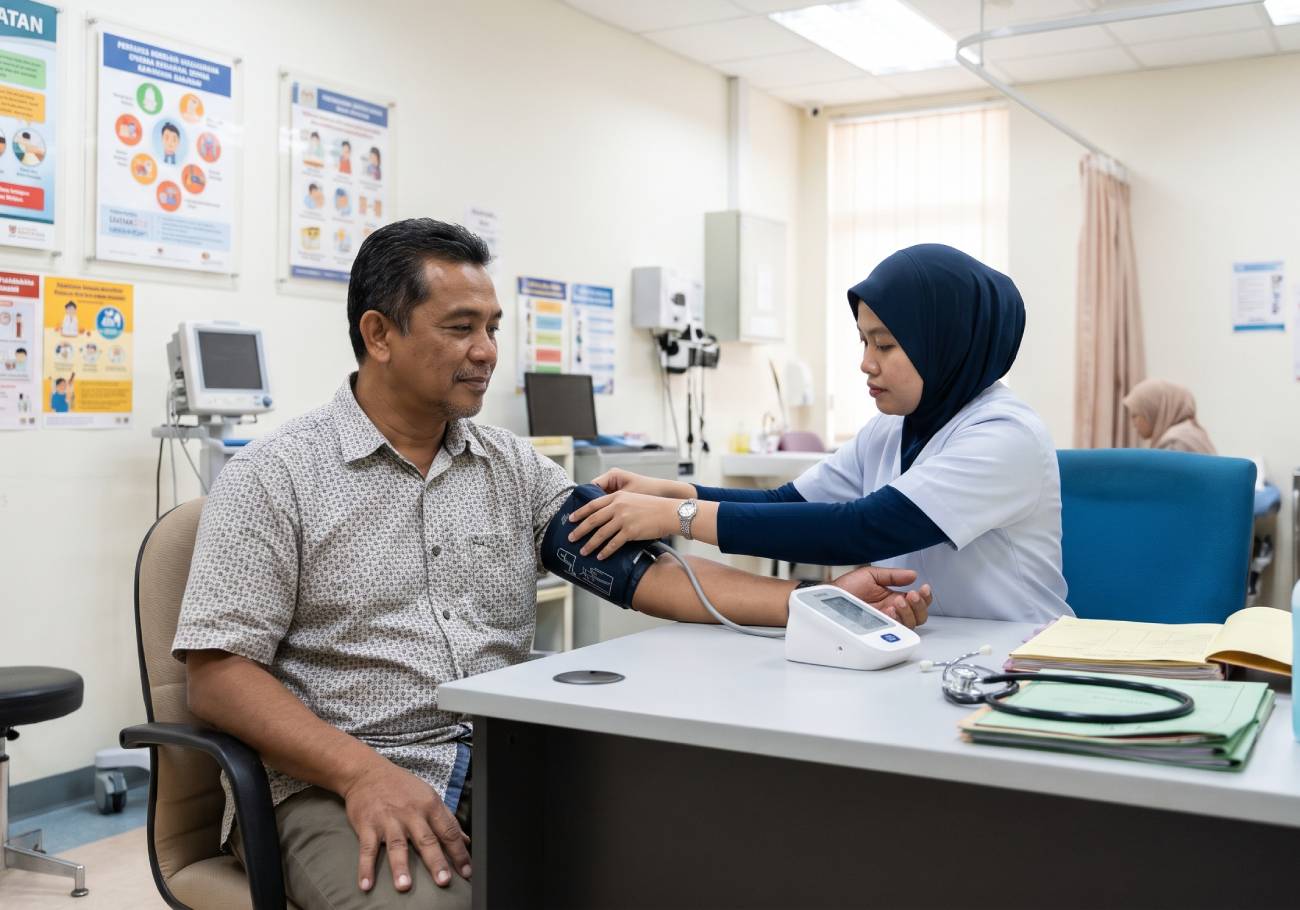
Medical insurance, often called health insurance, helps cover eligible expenses related to healthcare. Depending on the policy, coverage may include consultations with doctors, hospital admissions, diagnostic tests, surgery, prescribed treatments, and specialist services. Some plans provide benefits for preventive care, vaccinations, and health screenings, though the availability of these services varies between policies. Medical insurance can reduce the amount an individual must pay personally when treatment is needed. This can be particularly helpful when an illness or injury requires repeated consultations, expensive medication, or an extended hospital stay. Coverage limits, deductibles, co-payments, waiting periods, and exclusions affect the amount an insurer pays. Reviewing these conditions gives policyholders a clearer picture of the financial support available when healthcare needs arise.
The Main Differences Between Life and Medical Insurance
The main difference between these insurance types lies in the risks they address. Life insurance provides financial benefits to designated beneficiaries following the insured person’s death, subject to the contract’s requirements. Medical insurance helps pay for covered healthcare services while the insured person is alive. The timing of their benefits differs, too. A life insurance death benefit is usually paid after a valid claim following the policyholder’s death, whereas medical insurance may pay eligible treatment costs directly to a healthcare provider or reimburse the policyholder. Their financial functions differ as well. Life insurance can help replace lost income and protect dependents from future financial difficulties. Medical insurance focuses on managing healthcare expenses that might otherwise reduce savings or require borrowing. Having one type of coverage does not automatically provide the protection offered by the other.
Understanding Costs and Financial Benefits
Life insurance premiums are influenced by factors such as age, health, smoking status, coverage amount, policy duration, and the type of plan selected. Medical insurance premiums may reflect age, the benefits provided, coverage limits, medical history, and other conditions specified by the insurer. Both types of policies require careful budgeting, since premiums must remain affordable over time. Certain life insurance plans include a savings component, but these products may carry higher costs and surrender charges. Medical insurance is not normally designed to build savings or generate investment returns. Its primary function is to help cover eligible medical expenses. People should assess the actual benefits, exclusions, fees, and payment obligations before deciding which policy offers suitable value for their circumstances.
Why Having Both Types of Insurance Can Help
Life and medical insurance can work together to provide broader financial protection. Medical coverage helps manage treatment expenses, reducing the risk of large healthcare bills affecting household savings. Life insurance provides financial assistance to beneficiaries if the insured person dies, helping dependents meet ongoing obligations. A family with young children, a mortgage, or substantial shared expenses may need both forms of protection. A single adult with limited financial responsibilities may require a different combination of benefits. Insurance needs can change after marriage, childbirth, a property purchase, a career change, or an increase in household income. Reviewing coverage at these stages helps people identify gaps and adjust their protection to reflect their current responsibilities.
Reviewing Policy Terms Before Buying
Before purchasing insurance, individuals should read the policy documents carefully and check the conditions that apply to claims. Life insurance buyers should review the death benefit, premium schedule, exclusions, policy duration, and any conditions affecting payment. Medical insurance buyers should examine hospital coverage, treatment limits, deductibles, co-payments, waiting periods, and exclusions for particular conditions. They should check whether preferred doctors and hospitals are included in the insurer’s network. It is useful to compare several plans and ask the provider to explain any unclear terms. Financial advisers or insurance representatives can help clarify the available options, though the final decision should reflect the individual’s needs, financial capacity, and understanding of the contract.
Conclusion
Life insurance and medical insurance offer different forms of financial protection, making each useful for a separate set of needs. Life insurance helps protect beneficiaries from financial hardship following the policyholder’s death, whereas medical insurance helps manage eligible healthcare expenses during the insured person’s lifetime. Choosing suitable coverage requires an assessment of family responsibilities, income, savings, existing benefits, and future financial commitments. Regular policy reviews can help keep protection aligned with changing circumstances. By understanding the purpose, costs, limitations, and benefits of each insurance type, individuals can make informed decisions and build a financial plan that offers greater security for themselves and their families.


 Maran Perianen
 Navin Kumar Perianen

Add comment